Purchasing a term insurance policy is fundamentally different from buying motor or health insurance. With car or medical coverage, you are alive and present to manage the paperwork, follow up with surveyors, and negotiate with the insurance company. With a term life plan, the actual product—the death benefit payout—will only be triggered when you are no longer around to guide your family.
Because your spouse, parents, or children will have to navigate the claim settlement process during an emotionally devastating time, selecting the cheapest online quote can be a grave mistake. Choosing a reliable provider coupled with a dedicated local advisor in Faridabad ensures that the ₹1 Crore+ promise on your policy bond translates smoothly into your family’s bank account.
How to Select the Right Term Insurance Provider
Key Benchmarks for Term Life Selection
When selecting a term insurance provider in faridabad, prioritize insurers with a Claim Settlement Ratio above 98%, an Amount Settlement Ratio above 95%, and reliable local support for your nominees. Ensure your family’s financial security with expert advice from Faridabad Insurance Wala, where we oversee accurate medical disclosures at the time of purchase and provide hands-on, doorstep assistance to your family during the claim process.
3 Quantitative IRDAI Metrics You Must Check Before Buying
Every year, the Insurance Regulatory and Development Authority of India (IRDAI) publishes audited performance data for all life insurers. Instead of relying on celebrity advertisements, evaluate your prospective insurer against these three financial parameters:
1. Claim Settlement Ratio (CSR) by Count
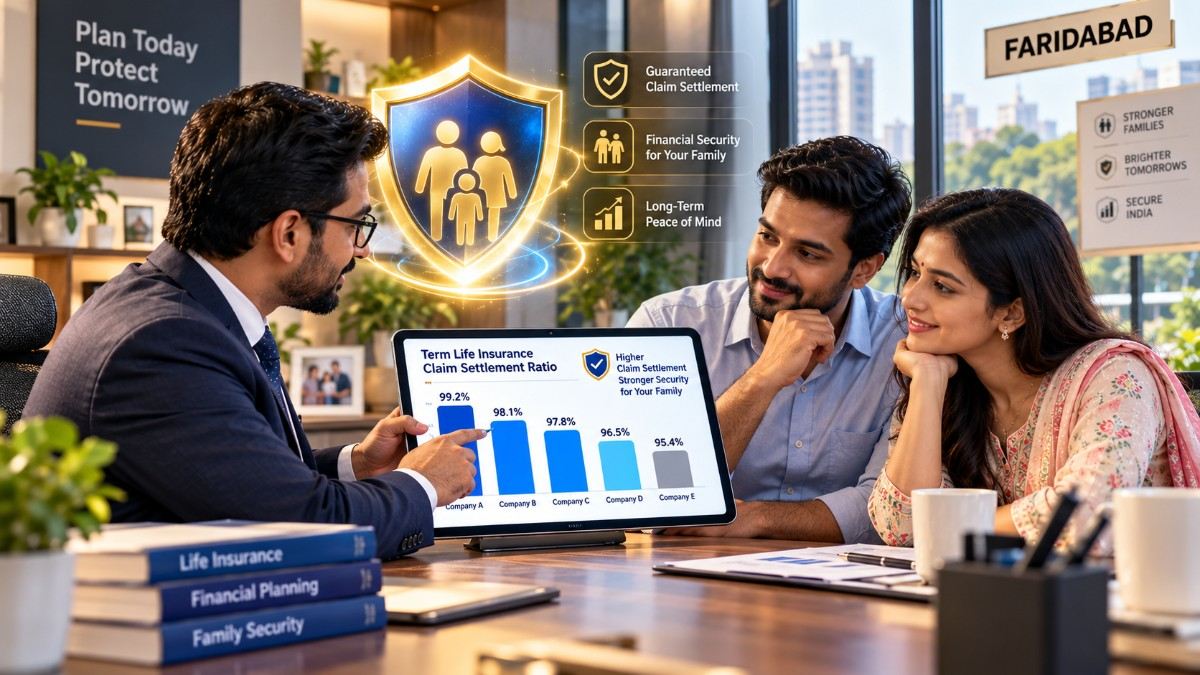
The Claim Settlement Ratio measures the percentage of total death claims an insurer approves out of every 100 claims received in a financial year. Always select a life insurance company that maintains a consistent 3-year average CSR of 98% or higher. A high CSR demonstrates that the company has a culture of honoring legitimate claims rather than searching for minor technicalities to reject them.
2. Amount Settlement Ratio (ASR) by Value
A high CSR alone doesn’t tell the full story. Some insurers settle thousands of small ₹2 Lakh endowment policies quickly to boost their CSR percentage, while rejecting high-value ₹1 Crore and ₹2 Crore term insurance claims. The Amount Settlement Ratio (ASR) measures the total monetary value of claims paid against total monetary claims received. Look for an ASR consistently exceeding 95%.
3. Solvency Ratio
A term plan is a 30-to-40-year contract. You need certainty that the insurer will remain financially solvent decades from now, even in the event of a widespread catastrophe or pandemic. The IRDAI mandates a minimum solvency ratio of 1.5 (150%). Top-tier private and public insurers in India maintain solvency ratios between 1.8 and 2.2+.
Comparison: Local Advisory vs. Direct Online Portals for Nominees
When an unfortunate event occurs, the difference between having a trusted neighborhood advisor in Faridabad and relying on a remote toll-free number becomes starkly evident:
| Stage of Policy | With Faridabad Insurance Wala | Direct Online Aggregator Portals |
|---|---|---|
| Proposal & Medical Disclosure | Thorough clause-by-clause audit of health history, habits, and income to prevent future Section 45 disputes. | Rushed call-center tele-underwriting where agents often skip medical disclosures just to close the sale. |
| Nominee Awareness | Your family knows our local office address and has a direct contact person in Faridabad. | Nominees are often unaware of login credentials or which toll-free queue to dial. |
| Death Claim Documentation | On-ground assistance collating Municipal Death Certificates, hospital records, and physician statements. | The grieving family must scan, upload, and courier physical documents to a regional hub on their own. |
| Branch & Zonal Follow-up | Direct liaison with local insurer branch managers in Faridabad/NCR to expedite payout clearance. | Impersonal automated email tickets and rotating customer care executives. |
The Biggest Reason Term Claims Get Rejected: Non-Disclosure
Under Section 45 of the Insurance Act, an insurer cannot call a life insurance policy into question after 3 years of continuous coverage—except on grounds of proven fraud or deliberate suppression of material facts. Nearly 90% of early term insurance claim rejections happen because the buyer hid pre-existing medical conditions (like diabetes, hypertension, or past surgeries), smoking/alcohol habits, or existing policies during application.
When you structure your policy through our local desk, we ensure every single medical test report, ITR document, and lifestyle declaration is transparently recorded and accepted by the underwriter upfront. You may pay a slight medical loading if you have a pre-existing condition, but your family’s final claim becomes 100% indisputable.
Essential Riders to Customize Your Term Policy
- Waiver of Premium on Disability/Critical Illness: If an accident or severe illness leaves you permanently unable to earn, the insurer waives all future premiums while keeping your ₹1 Crore+ life cover active.
- Accidental Death Benefit (ADB): Provides an additional lump-sum payout over and above the base sum assured in the event of a fatal road or workplace accident.
- Critical Illness Rider: Pays an immediate living lump sum upon diagnosis of major illnesses like cancer, cardiac arrest, or stroke to cover treatment at premier hospitals across Faridabad.
Secure Indisputable Protection for Your Family
Don’t leave your family’s financial future to automated web portals. Contact Faridabad Insurance Wala to compare top IRDAI-rated term insurance providers and lock in a rock-solid policy backed by lifelong local support.
Compare Term Plans With an Expert