When walking into an insurance discussion or exploring options online, families across Faridabad are frequently met with a confusing array of acronyms and policies: traditional endowment plans, Unit Linked Insurance Plans (ULIPs), money-back policies, and pure term protection. Many buyers end up mixing insurance with investment, resulting in inadequate financial coverage and low compound returns.
To secure your household’s financial future without overpaying, it is essential to look past marketing pitches and understand how traditional life insurance structures differ fundamentally from pure risk protection.
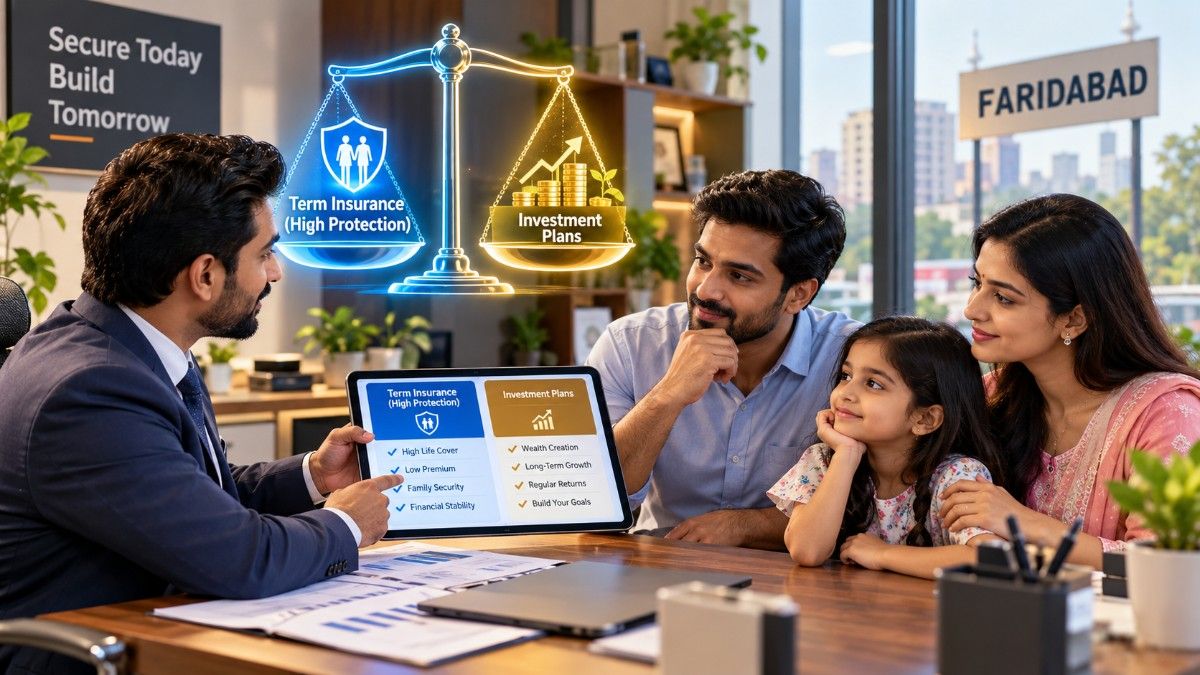
Term Insurance vs. Investment-Linked Policies
Risk Protection vs. Investment Returns
While traditional life insurance combines risk cover with investment returns, term insurance provides massive financial protection at a fraction of the cost. Let Faridabad Insurance Wala help you design a portfolio that perfectly balances savings and security by keeping insurance and investment strictly separate.
What is Pure Term Life Insurance?
Term insurance is the purest, most transparent form of life insurance. You pay a fixed annual premium for a pre-determined timeframe (e.g., until age 60 or 65). If the policyholder passes away during this active term, the insurance company pays out a massive lump-sum death benefit (such as ₹1 Crore or more) to the nominee.
- No Maturity Benefit: If you survive the policy term, you receive no payout (unless you purchase a specialized “Term with Return of Premium” variant). Because there are no investment components or savings returns built in, the premiums are exceptionally low.
- Maximum Coverage for Minimum Cost: A 30-year-old can secure a ₹1 Crore term cover for less than ₹1,000 to ₹1,200 per month, making it the most affordable way to create an instant financial safety net.
What Are Traditional Savings and Investment-Linked Policies?
Investment-linked products bundle life insurance with market-linked or fixed-return savings schemes. These include:
- Endowment Plans: Traditional policies that promise a lump sum upon maturity if you survive, alongside a payout if you pass away. However, their internal rate of return (IRR) is typically low (around 4% to 5%).
- ULIPs (Unit Linked Insurance Plans): Plans that split your premium between life cover and equity/debt mutual funds. While they offer market-linked growth, high allocation charges, mortality deductions, and administrative fees can eat into long-term compounding.
Head-to-Head Comparison: Term Insurance vs. Endowment vs. ULIP
Comparing these structures side-by-side reveals why financial advisors universally recommend keeping insurance and investments separate:
| Feature | Pure Term Insurance | Endowment / Money-Back | ULIP (Unit Linked Plan) |
|---|---|---|---|
| Primary Objective | Pure risk protection & income replacement. | Guaranteed savings with minor life cover. | Market-linked wealth creation with life cover. |
| Life Cover Payout | Very High (₹1 Cr to ₹5 Cr for low cost). | Very Low (Usually 10x of annual premium). | Moderate (Typically 10x of annual premium). |
| Maturity Returns | Zero (unless Return of Premium add-on is chosen). | Guaranteed, but low returns (4% to 5% IRR). | Market-linked returns (depends on equity/debt fund performance). |
| Transparency & Cost | High transparency; lowest cost per lakh of cover. | Low transparency; high cost structure. | Moderate transparency; subject to market risks & fund charges. |
The Golden Rule: “Buy Term and Invest the Rest”
Financial experts advocate a simple, powerful strategy: purchase a pure high-cover term plan to protect your dependents against unexpected tragedy, and channel your remaining surplus funds into dedicated, high-performing wealth vehicles like Equity Mutual Funds, Public Provident Fund (PPF), or National Pension System (NPS).
By separating insurance from investment, you achieve massive life cover while generating superior long-term returns for your retirement and your children’s education.
Design a Balanced Financial Portfolio
Don’t let high-cost traditional policies shortchange your family’s financial security. Contact Faridabad Insurance Wala to calculate your Human Life Value (HLV) and structure an optimal term insurance plan.
Consult Our Term Insurance Experts