Many households across Faridabad signed up for basic health insurance policies years ago—often settling for low sum insured limits, rigid room rent caps, or corporate group mediclaim plans that vanish the moment an employee switches jobs. As medical inflation accelerates and family healthcare needs evolve, holding onto an outdated policy can leave you dangerously exposed during a major medical crisis.
When you decide to upgrade your protection or port your existing policy to a modern insurer, knowing which advanced clauses to look for makes all the difference. Evaluating your choices against benchmark industry standards ensures your new policy delivers seamless financial protection.
Essential Features of a Superior Mediclaim Policy
What to Prioritize During Portability
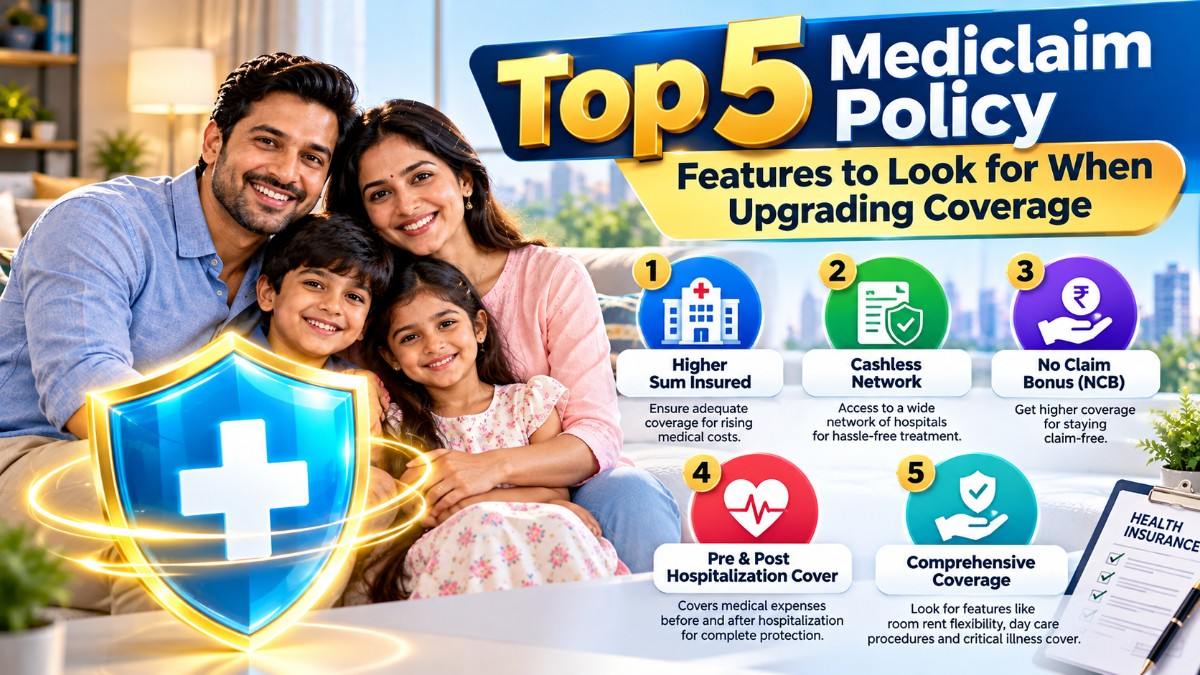
The top 5 mediclaim policy features include zero room rent capping, automatic sum insured restoration, minimal waiting periods, comprehensive daycare coverage, and unlimited cashless hospital access. Upgrade your family’s protection with Faridabad Insurance Wala.
1. Zero Room Rent Capping (No Proportional Deductions)
Older or budget-tier health policies frequently impose a room rent sub-limit, restricting your daily hospital room rent to 1% or 2% of the sum insured. If your policy has a ₹5,000 room cap and you opt for an ₹8,000 room during hospitalization, the insurer doesn’t just deduct the ₹3,000 difference; they apply proportional deductions across your entire medical bill—slashing surgeon fees, diagnostics, and pharmacy costs by the same percentage. Upgrading to a modern plan with absolute zero room rent restrictions eliminates this hidden financial trap.
2. Automatic Sum Insured Restoration
Medical emergencies rarely happen in isolation. If a family member exhausts a ₹10 Lakh sum insured midway through the year due to an intensive hospitalization, what happens if another emergency occurs months later? Basic plans leave you unprotected. Modern policies feature automatic sum insured restoration, which instantly refills 100% of your coverage limit for subsequent, unrelated hospitalizations within the same policy year at no extra charge.
3. Minimized Waiting Periods & Pre-Existing Disease Credit
Standard health insurance policies carry a 2-to-4-year waiting period before covering pre-existing conditions (PED) like diabetes, thyroid issues, or hypertension. Under IRDAI portability regulations, when you switch insurers, your new provider must give you credit for the waiting periods you have already completed. When upgrading, look for policies offering shorter baseline PED waiting periods or optional riders to reduce this timeframe further.
4. Comprehensive Daycare Treatment Coverage
Decades ago, health insurance only paid out if a patient was admitted to a hospital for a minimum of 24 consecutive hours. Today, modern medical advancements—such as cataract surgeries, chemotherapy, dialysis, lithotripsy, and minor laparoscopic procedures—are completed as daycare treatments taking only a few hours. Ensure your upgraded policy covers 500+ daycare procedures without requiring a 24-hour hospital stay.
5. Unlimited Cashless Hospital Access Across Faridabad & NCR
A policy is only as reliable as its cashless network hospital availability. When upgrading, verify that your insurer maintains direct ties with major local tertiary care centers in Faridabad and Delhi-NCR—such as Asian Institute of Medical Sciences, Metro Heart Institute, Fortis Escorts, and Marengo Asia (QRG) Hospital—allowing your family to check in and out without scrambling to arrange out-of-pocket cash.
Comparison: Basic Legacy Plan vs. Upgraded Modern Mediclaim
See how an outdated legacy policy stacks up against a modern, feature-rich health insurance upgrade:
| Policy Parameter | Basic Legacy Mediclaim Plan | Upgraded Modern Health Policy |
|---|---|---|
| Room Rent Limits | Strict sub-limits (1% to 2% of sum insured) with proportional deductions. | Zero room rent capping (choose any standard private room). |
| Sum Insured Refill | None. Once exhausted, coverage ends for the year. | Automatic 100% restoration for subsequent claims. |
| Daycare Procedures | Limited list; strictly enforces 24-hour hospitalization. | 500+ modern daycare treatments covered without 24-hr stay. |
| Consumables Expenses | Excluded (PPE kits, gloves, and disposal items paid by patient). | Covered under modern consumables riders. |
| Health Check-ups | Rarely included or subject to strict limits. | Complimentary annual preventive health check-ups. |
How the IRDAI Portability Process Works
Upgrading or shifting your health insurance policy to a better insurer without losing your accumulated benefits is fully protected under IRDAI guidelines:
- Apply 45 Days Before Renewal: Submit your portability request to your new chosen insurer at least 45 days prior to your current policy’s expiry date.
- Transfer Waiting Period Credits: Your previous insurer must transfer your continuous coverage history, ensuring your completed waiting periods for pre-existing diseases carry over seamlessly.
- No fresh medical underwriting is required for the equivalent sum insured amount; underwriting only applies if you request a higher sum insured upgrade.
Ready to Upgrade Your Family’s Health Insurance?
Don’t stay locked into a restrictive legacy policy with hidden sub-limits. Contact Faridabad Insurance Wala to evaluate your current coverage and port seamlessly into a modern, comprehensive health plan.
Consult Our Health Insurance Experts