Letting your car insurance expire exposes you to sudden e-challans from automated traffic cameras across Haryana and Delhi-NCR. Beyond statutory fines, the moment a policy lapses past its renewal deadline, you enter a break-in period where an insurer will not issue comprehensive coverage instantly. Before activating Own Damage protection, the insurance company requires a formal vehicle inspection.
Understanding how the inspection workflow operates—and how to navigate digital self-inspection apps without getting your submission rejected—ensures your vehicle is protected without unnecessary delays.
How Vehicle Inspection Works for Expired Policies
Vehicle Break-In Inspection Explained
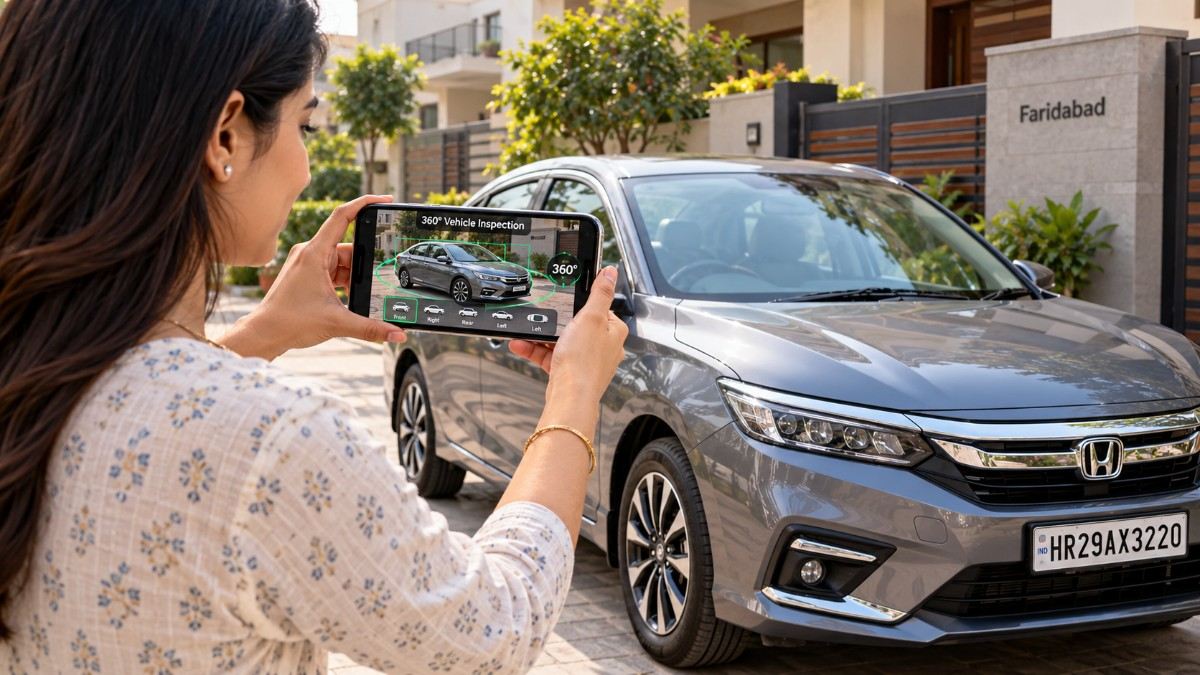
For a car insurance renewal after expiry, insurance companies mandate a physical or digital self-inspection to document pre-existing damages before reinstating Own Damage and comprehensive coverage. Modern insurers provide an app or secure web link allowing owners to record a continuous 360-degree video and upload odometer, engine, and chassis photos. Let the experts at Faridabad Insurance Wala guide you through a fast, hassle-free approval process to get you safely back on the road.
Why Do Insurers Insist on an Inspection After Expiry?
When you renew your policy on or before the due date, coverage continues seamlessly because there was no break in tenure. The insurer assumes the vehicle remained in its insured state throughout.
However, when a policy lapses even by a single day, an underwriting risk gap opens. Insurance companies must verify that the vehicle was not involved in an accident during the uninsured window. The inspection records every pre-existing scratch, dent, glass chip, or bumper misalignment. If you file a claim later, pre-existing damages documented during the break-in inspection will be excluded from settlement.
Digital Self-Inspection vs. Physical Surveyor Visit
Vehicle owners in Haryana typically have two pathways to complete their break-in inspection, depending on how long the policy has been expired:
| Inspection Parameter | Digital Self-Inspection (Smartphone App) | Physical Surveyor Inspection |
|---|---|---|
| Lapse Duration Eligible | Policies expired up to 60 to 90 days. | Policies expired over 90 days or high-value luxury cars. |
| Inspection Timeframe | Self-recorded in 10 to 15 minutes by the owner. | Requires scheduling an in-person surveyor appointment. |
| Approval Turnaround | Fast digital underwriting (usually 2 to 4 hours). | 24 to 48 hours following surveyor report submission. |
| Inspection Charges | Typically ₹0 (Free digital processing). | May include surveyor inspection charges (₹250 – ₹500). |
| Common Rejection Causes | Poor sunlight, blurry chassis stamping, interrupted video. | Surveyor scheduling mismatches or vehicle unavailability. |
Step-by-Step: How to Complete a Digital Self-Inspection Successfully
Most break-in rejections happen due to minor technical mistakes when capturing photos and video. Follow these sequential steps for smooth approval on your first attempt:
- Park in Open Daylight: Move your vehicle into clear, outdoor natural light. Avoid basement parking lots, carports, or nighttime recordings where shadows obscure body panels.
- Clean Your Car and Windshield: Dirt and mud splatters can be mistaken for scratches or cracks by automated AI underwriting scanners, leading to inspection rejections.
- Locate and Clean the Chassis Number: The stamped metal Vehicle Identification Number (VIN)—usually etched under the driver’s seat carpet, in the engine bay, or behind the front windshield—must be legible and sharp.
- Record a Continuous 360-Degree Video: Start recording from the front corner as instructed by the insurer’s app, walking around the car in one continuous circular motion without stopping or pausing the recording.
- Capture Mandated Close-Up Stills: Take clear, focused photographs of the odometer reading (showing total kilometers), engine bay, tire treads, front windshield, and rear glass.
What Happens to Your Add-ons and NCB During Inspection?
Renewing an expired car policy involves two critical underwriting rules:
1. The 90-Day No Claim Bonus (NCB) Rule
If your policy has been expired for fewer than 90 days, your accumulated No Claim Bonus (from 20% up to 50%) remains fully intact once the inspection is approved. If the lapse reaches Day 91, your NCB discount permanently resets to 0%, significantly increasing your renewal premium.
2. Zero Depreciation Add-on Eligibility
If your car is under 5 years of age and the inspection confirms no structural or body damage, most insurers allow you to retain or add Zero Depreciation. However, if the inspection reveals extensive unrepaired accidental dents, underwriters may decline Zero Dep or issue a policy with an own-damage exclusion endorsement on those specific panels.
Need to Fast-Track Your Car Inspection?
Don’t let inspection rejections keep your car off the road. Contact Faridabad Insurance Wala to get quick break-in inspection links, expert document assistance, and seamless policy reinstatement.
Fast-Track Your Inspection Today