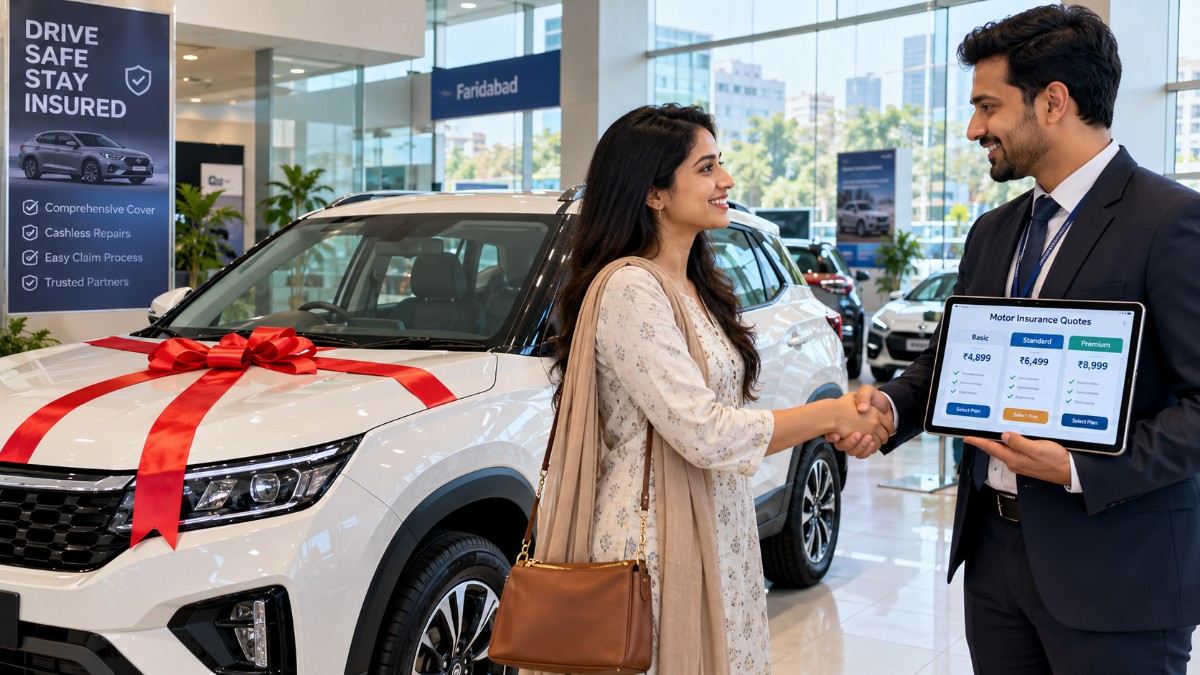
Taking delivery of a new car is one of the most exciting milestones for any family. However, during the final pricing negotiations at car showrooms across Mathura Road and Delhi-NCR, buyers are routinely handed an on-road quotation sheet where insurance costs appear unusually steep.
Many dealership sales executives claim that in-house insurance is mandatory for delivery or that opting out will void manufacturer warranties. Neither claim is legally accurate under Indian regulations. Understanding the true mechanics behind new vehicle policies allows you to secure identical protection while saving thousands of rupees on day one.
Where Should You Buy Your New Car Insurance?
Dealership Insurance vs. Independent Advisory
When you buy insurance for new car deliveries, dealership quotes often bundle broker markups and redundant riders that inflate premiums by 25% to 40%. The Competition Commission of India (CCI) and IRDAI confirm that buyers are legally entitled to purchase coverage independently from any authorized insurer without impacting factory warranties. By consulting Faridabad Insurance Wala, you can secure identical zero-depreciation coverage, engine protect riders, and return-to-invoice protection at fair market rates with direct local claim support.
The Legal Truth: You Are Never Forced to Buy From the Dealer
Car dealerships earn substantial commissions on retail motor insurance sales. To maximize these margins, sales desks often tell first-time buyers that external insurance policies delay registration or complicate cashless claims. Here is what statutory guidelines in India actually mandate:
- Freedom of Choice: Under circulars issued by the Competition Commission of India (CCI) and the Insurance Regulatory and Development Authority of India (IRDAI), tying vehicle sales to mandatory dealer-sourced insurance is illegal.
- No Impact on Vehicle Warranty: Your vehicle’s mechanical and electrical warranties are provided by the car manufacturer (OEM), not the insurance underwriter. Buying insurance outside the showroom does not void standard or extended manufacturer warranties.
- Seamless RTO Registration: Regional Transport Offices (RTOs) require a valid motor insurance certificate showing the chassis and engine number to issue registration plates. An external policy document is 100% compliant for vehicle delivery.
Comparison: Showroom Package vs. Independent Local Policy
Examining the structural details of both channels reveals how purchasing through an independent local advisor delivers better value and dedicated advocacy:
| Factor | Showroom / Dealer Insurance | Independent Policy (Faridabad Insurance Wala) |
|---|---|---|
| Pricing Transparency | Fixed retail rate with integrated showroom margins. | Transparent pricing based on actual insurer risk ratings (up to 40% lower). |
| Add-on Selection | Bundled pre-selected riders you may not need. | Customized add-ons (Zero Dep, RTI, Engine Cover, Consumables). |
| Insurer Options | Restricted to 2 or 3 tie-up partners of that dealership. | Access to multiple leading IRDAI-regulated general insurance carriers. |
| Claim Support | Handled by showroom staff; limited post-delivery relationship. | Dedicated on-ground intermediary advocacy during repair disputes. |
| Multi-Year Terms | Mandatory 3-year Third Party + 1-year Own Damage schedule. | Accurately structured statutory 3+1 cover without unnecessary markups. |
3 Essential Add-Ons Every New Car Needs
Under IRDAI rules, brand-new private cars in India must carry a mandatory 3-year Third-Party liability policy alongside a 1-year Own Damage (OD) component. When purchasing your new car insurance, skipping critical add-on covers can leave costly coverage gaps. Prioritize these three riders:
1. Zero Depreciation (Bumper-to-Bumper)
Standard insurance applies statutory depreciation of 50% on plastic/rubber components and up to 30% on fiberglass parts during collision repairs. Zero Depreciation ensures that the insurer pays 100% of replacement part costs without material cuts.
2. Return to Invoice (RTI)
If your vehicle is stolen or suffers a constructive total loss during its first few years, standard IDV settlements deduct depreciation from the ex-showroom value. Return to Invoice bridges the entire difference, reimbursing the complete original invoice value—including road tax and registration charges paid at delivery.
3. Engine and Gearbox Protector
Monsoon waterlogging across low-lying roads can cause hydrostatic lock if water enters the air intake. Standard policies classify water damage to the engine as “consequential loss” and reject claims. An Engine Protect rider guarantees full coverage for engine rebuilds and transmission damage.
Step-by-Step: How to Buy Your New Car Policy Independently
Securing your own car insurance before taking delivery is straightforward:
- Request the Vehicle Details: Once your vehicle allocation is confirmed, ask the dealer for the official allotment letter containing the Chassis Number and Engine Number.
- Get a Comparative Quote: Share the vehicle model, variant, and chassis details with Faridabad Insurance Wala to evaluate competitive, add-on-loaded coverage across top insurers.
- Issue the Policy Document: The policy is generated digitally within minutes using the allocated chassis number.
- Provide Document to Dealer: Hand a copy of the policy to the dealership coordinator to complete RTO road-tax submission and proceed with final vehicle delivery.
Save Up to 40% on Your New Car Insurance
Do not pay inflated showroom prices for your new vehicle coverage. Contact Faridabad Insurance Wala to compare comprehensive, zero-depreciation quotes across top IRDAI-approved carriers and protect your new drive with complete peace of mind.
Get an Instant New Car Quote