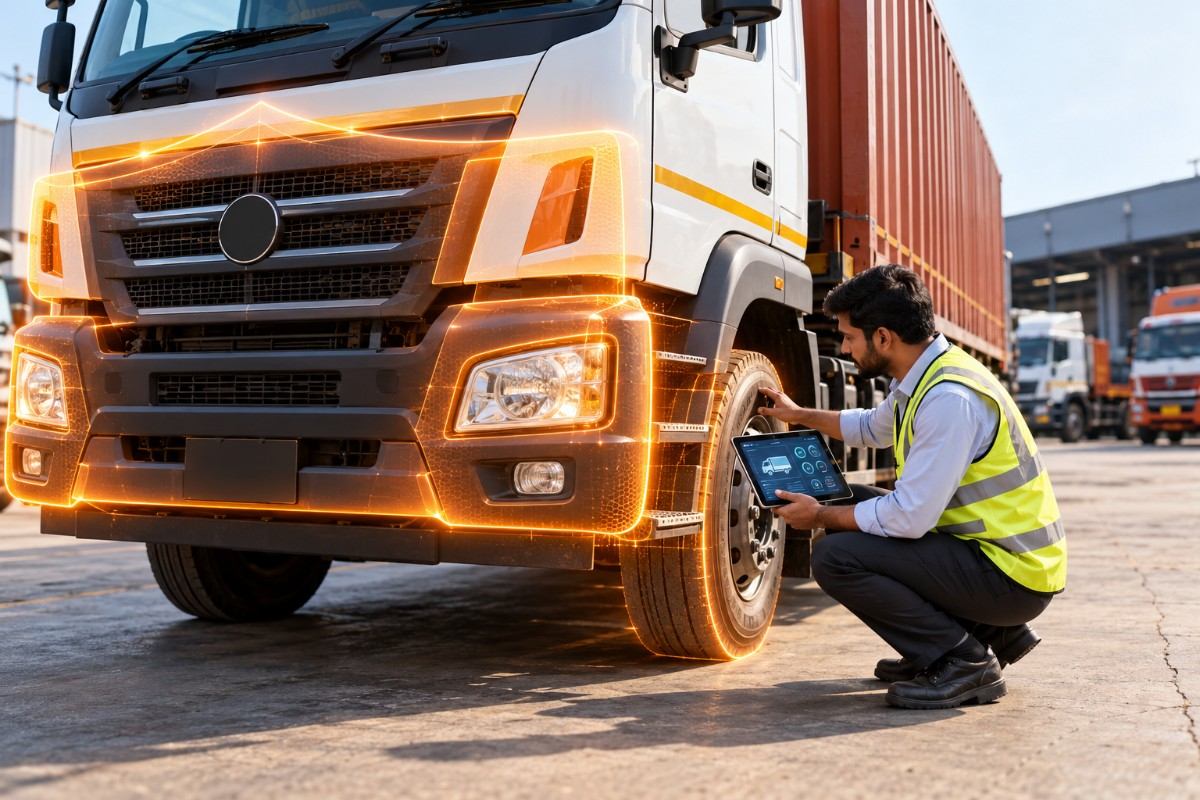
Operating a transport fleet along the industrial corridors of Faridabad and Mathura Road exposes commercial vehicles to constant wear and tear. Unlike private cars, goods-carrying and passenger commercial vehicles face heavy daily usage on rough terrain, making their exterior parts highly susceptible to damage.
Many fleet operators discover a glaring gap in their coverage only after a minor collision: standard commercial motor policies exclude specific external components. This is where the IMT 23 premium meaning becomes critical. Adding this specific IRDAI-approved endorsement protects your fleet from significant out-of-pocket expenses during partial loss claims.
What is the IMT 23 Add-On?
Defining the IMT 23 Premium
- The Core Definition: IMT 23 is a specific endorsement tariff for commercial vehicles that extends insurance coverage to highly vulnerable external parts that are strictly excluded under standard commercial policies.
- Parts Covered: The endorsement protects lamps, headlights, tyres and tubes, mudguards, the bonnet, side parts, bumpers, and the painting of the damaged portion.
- Financial Benefit: Standard policies offer 0% claim coverage for these parts. Paying the nominal IMT 23 premium guarantees that the insurer will cover at least 50% of the replacement and repair costs for these items during accidental damage.
- Who Needs It: Essential for trucks, delivery vans, passenger buses, and taxis operating in dense urban traffic or construction zones where minor exterior damage is frequent.
Why Do Standard Policies Exclude These Parts?
To understand the value of IMT 23, you must first understand commercial vehicle underwriting. Because commercial vehicles drive significantly higher mileage than private cars, parts like bumpers, mudguards, and tyres undergo extreme daily wear and tear.
Insurance companies view damage to these components as a highly probable operational risk rather than an unexpected accident. Therefore, to keep the base Own Damage (OD) premium affordable, insurers universally exclude these parts from standard comprehensive commercial vehicle claims. If your delivery truck rear-ends another vehicle, breaking the headlights and bumper, a standard policy will not pay for those specific parts.
The Coverage Difference: With vs. Without IMT 23
Adding the IMT 23 clause bridges this costly gap. Here is exactly how your claim payout changes when you opt for this endorsement:
| Vehicle Component | Standard Commercial Policy Payout | Payout with IMT 23 Endorsement |
|---|---|---|
| Lamps & Headlights | 0% (Excluded) | Up to 50% of replacement cost. |
| Bumpers (Front/Rear) | 0% (Excluded) | Up to 50% of replacement cost. |
| Mudguards & Side Panels | 0% (Excluded) | Up to 50% of replacement cost. |
| Tyres and Tubes | Excluded (unless stolen with the vehicle) | Up to 50% (if damaged in an accident). |
| Paintwork on Damaged Parts | 0% (Excluded) | Up to 50% of the painting cost. |
How is the IMT 23 Premium Calculated?
The IMT 23 premium is calculated as a small percentage of your vehicle’s base Own Damage (OD) premium, rather than a flat fixed fee. Because it mitigates substantial repair costs, the slightly higher upfront premium pays for itself during the first minor traffic collision.
If you are operating a fleet, not having this endorsement means your maintenance budget will bear the brunt of every broken headlight, cracked bumper, and damaged mudguard across all your vehicles. Over an annual cycle, these “minor” out-of-pocket expenses can devastate a logistics company’s profit margins.
Secure Your Fleet’s Most Vulnerable Parts
Don’t let minor exterior damages drain your business revenue. Contact Faridabad Insurance Wala to add IMT 23 premium coverage to your policy and ensure comprehensive protection for your commercial vehicles.
Get a Custom Commercial Quote